Flood disclosure form requirements have become more important for property transactions as Florida joined the growing number of states mandating transparency about flood risks. The Natural Resources Defense Council reports that states requiring flood disclosures have steadily increased since 2017, but the laws vary widely throughout the country. While 29 states have some form of flood disclosure requirements, 21 states have none. Those relocating from Miami to Los Angeles need to understand the differences between the florida flood disclosure form and california flood disclosure form. Florida's new flood disclosure form contrasts sharply with California's complete natural hazard disclosure approach, which includes the california tenant flood hazard disclosure form and flood zone disclosure form requirements. Navigating these varying regulations requires careful attention to protect buyers and renters from unexpected financial risks.
Understanding Flood and Hazard Disclosure Laws in Both States
"A national flood history disclosure requirement would ensure a consistent level of protection for buyers and renters, regardless of location." — ASFPM, Advocacy organization for floodplain management
Federal law does not require residential landlords or sellers to disclose flood hazards to prospective buyers or renters. Individual states establish their own requirements. Approximately two-thirds of U.S. states require property sellers to disclose flood risk to buyers, though landlords face fewer disclosure requirements than property sellers.
Florida enacted Senate Bill 948 in 2025, codified as Florida Statutes Sections 83.512 and 689.302. This established the new florida flood disclosure form requirements. Sellers must complete and provide the florida flood disclosure form to purchasers at or before the sales contract execution. The disclosure mandates sellers indicate whether they filed insurance claims relating to flood damage. This includes claims with the National Flood Insurance Program and whether they received federal assistance from agencies like FEMA. Landlords entering lease agreements on or after October 1, 2025, with terms of one year or longer must provide similar disclosures.
California's approach is different through its Natural Hazard Disclosure Statement, enacted in 1998. The california flood disclosure form requirements fall under California Civil Code Section 1103. This mandates sellers disclose if properties are located in special flood hazard areas or areas of potential flooding. California property owners must disclose flood zone information if they have actual knowledge. This includes when mortgage holders require flood insurance or when owners currently carry such coverage. Assembly Bill 646 requires the california tenant flood hazard disclosure form for leases entered on or after July 1, 2018.
Comparing Florida Flood Disclosure Form and California Natural Hazard Disclosures

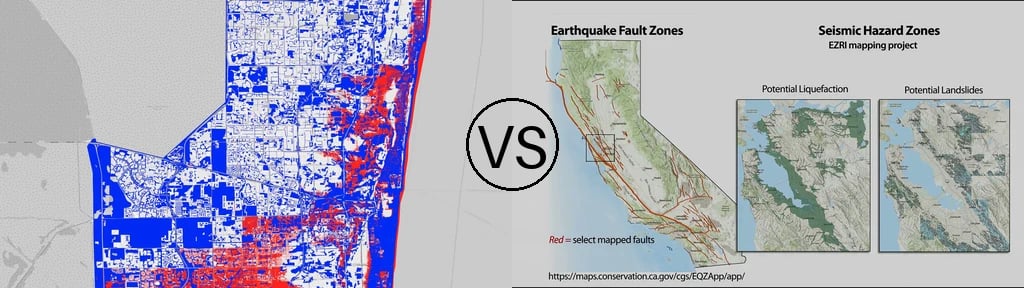
Image Source: Blog - pdfFiller
"The coastal hazards disclosure law is not accomplishing its statutory purpose." — Kevin Wozniak, J.D., LL.M., Environmental and Land Use Law Program, University of Florida Levin College of Law
The two states take fundamentally different approaches to hazard transparency. The new florida flood disclosure form addresses flooding exclusively. California's Natural Hazard Disclosure Statement covers six distinct hazard categories: special flood hazard areas, dam inundation zones, very high fire hazard severity zones, wildland fire areas, earthquake fault zones, and seismic hazard zones.
Florida sellers must complete the statutory florida flood disclosure form themselves. California permits third-party disclosure companies, licensed engineers, land surveyors, or geologists to prepare NHD reports on behalf of sellers. This third-party option costs between $50 and $150.
The florida flood disclosure form defines flooding broadly and covers overflow of inland or tidal waters, rapid accumulation of runoff from rivers or drainage ditches, and sustained standing water from rainfall. This expansive definition extends beyond FEMA-designated flood zones to include drainage and stormwater issues.
Consequences for non-disclosure differ significantly. California's incomplete NHD statements could result in damages up to the entire property value, while incomplete Transfer Disclosure Statements limit damages to repair costs. California buyers receive three days to rescind after late disclosures, extended to five days if mailed.
The florida flood disclosure form requires sellers to disclose all known flood damage during ownership from October 1, 2025, even without filed insurance claims. Condominium developers must provide similar flood history disclosures to unit buyers.
Practical Implications for Miami to LA Relocations
Luxury real estate transactions between Miami and Los Angeles unfold through private channels where discretion matters as much as property value. Yet even high-end relocations require attention to flood insurance mechanics that standard homeowners policies exclude.
Buyers securing federally backed mortgages in Special Flood Hazard Areas face mandatory flood insurance before closing. NFIP policies carry a 30-day waiting period from purchase, though this requirement waives when coverage connects to loan approval. This timing affects closing schedules, especially since force-placed insurance from lenders costs far more while protecting only the lender's interest.
Costs vary by location and elevation. Florida NFIP premiums range from $190 to over $2000 annually depending on coastal proximity, while policies in lower-risk zones average around $700. About 29% of NFIP claims originate outside designated high-risk flood areas. Miami neighborhoods like Brickell and Miami Beach carry higher flood exposure than Pinecrest or Coral Gables. Older waterfront properties face steeper premiums than code-compliant newer construction.
Private flood insurance offers competitive alternatives to NFIP with higher coverage limits and broader protection. Those who love to entertain know the right home makes all the difference. If you're thinking over a purchase in the near future or beginning your search, I'd love to help you find spaces designed for gracious living and effortless hosting. Christina Pope 📞 310-404-9931 ✉️ [email protected]
Comparison Table
Florida vs California: Flood and Natural Hazard Disclosure Requirements Comparison
Attribute | Florida Flood Disclosure Form | California Natural Hazard Disclosure |
Legal Framework | Senate Bill 948 (2025), codified as Florida Statutes Sections 83.512 and 689.302 | Natural Hazard Disclosure Statement under California Civil Code Section 1103 (enacted 1998) |
Effective Date | October 1, 2025 | July 1, 2018 (for tenant disclosures via Assembly Bill 646) |
Hazards Covered | Flooding exclusively (overflow of inland/tidal waters, rapid runoff accumulation, sustained standing water from rainfall) | Six distinct hazard categories: special flood hazard areas, dam inundation zones, very high fire hazard severity zones, wildland fire areas, earthquake fault zones, and seismic hazard zones |
Seller Disclosure Requirements | Must disclose all known flood damage during ownership, filed insurance claims (including NFIP), and federal assistance received (e.g., FEMA) | Must disclose if property is in special flood hazard areas or areas of potential flooding based on actual knowledge |
Who Completes the Form | Sellers must personally complete the statutory form | Third-party disclosure companies, licensed engineers, land surveyors, or geologists may prepare reports on behalf of sellers |
Third-Party Preparation Cost | Not mentioned | Typically $50-$150 |
Rental Property Requirements | Landlords must provide disclosure for lease agreements of one year or longer (effective October 1, 2025) | California tenant flood hazard disclosure form required for leases entered on or after July 1, 2018 |
Timing of Disclosure | At or before sales contract execution | Before or during property transfer |
Condominium Requirements | Condominium developers must provide similar flood history disclosures to unit buyers | Not specifically mentioned |
Consequences for Non-Disclosure | Not specifically detailed in this piece | Incomplete NHD statements could result in damages up to whole property value; incomplete Transfer Disclosure Statements typically limit damages to repair costs |
Buyer Rescission Rights | Not mentioned | Three days to rescind after late disclosures; extended to five days if mailed |
Scope Beyond FEMA Zones | Yes - extends beyond FEMA-designated flood zones to include drainage and stormwater issues | Actual knowledge forms the basis, including when mortgage holders require flood insurance or owners carry coverage |
Buyers who recognize luxury real estate opportunities between Miami and Los Angeles need to understand these disclosure requirements. Compliance matters, but strategic decision-making matters more. Luxury real estate in Los Angeles isn't driven by headlines. Private conversations, timing and access shape it. The most meaningful transactions often unfold quietly within trusted circles, where discretion carries as much weight as value.
Christina Pope
Sotheby's International Realty
📞 310-404-9931
✉️ [email protected]
EliteResidenceInternational.com
Conclusion
Relocating from Miami to Los Angeles means navigating two distinctly different disclosure frameworks. Florida's new flood-focused requirements contrast sharply with California's complete six-hazard approach. Both markets carry substantial natural risks. Understanding these differences protects buyers from unexpected insurance costs and property vulnerabilities. Buyers seeking guidance through luxury real estate transactions between these coastal markets will find that informed insight makes all the difference.
Christina Pope
Sotheby's International Realty
📞 310-404-9931
✉️ [email protected]
EliteResidenceInternational.com
Key Takeaways
Understanding the critical differences between Florida and California's flood and hazard disclosure laws is essential for anyone relocating between Miami and Los Angeles in 2026.
• Florida's new flood disclosure law (effective October 2025) requires sellers and landlords to reveal all flood damage history, insurance claims, and federal assistance—focusing exclusively on flooding risks.
• California takes a broader approach with its Natural Hazard Disclosure Statement, covering six distinct hazards including floods, earthquakes, wildfires, and dam inundation zones since 1998.
• NFIP flood insurance carries a 30-day waiting period and costs vary dramatically by location—from $190 to over $2,000 annually in Florida, with 29% of claims occurring outside high-risk zones.
• Non-disclosure consequences differ significantly: California buyers can claim damages up to the entire property value for incomplete disclosures, while also receiving 3-5 days to rescind after late disclosures.
• Third-party disclosure companies can prepare California's NHD reports ($50-$150), while Florida requires sellers to personally complete the statutory flood disclosure form.
While Florida's legislation represents a significant step toward transparency, California's multi-decade framework offers more comprehensive hazard protection. For luxury relocations between these coastal markets, working with experienced real estate professionals who understand both regulatory environments ensures informed decision-making and protects against unexpected financial exposure from natural hazards.
FAQs
Q1. What are the new flood disclosure requirements for property sellers in Florida? Florida's Senate Bill 948, effective October 1, 2025, requires sellers to complete a flood disclosure form at or before sales contract execution. Sellers must indicate whether they filed insurance claims for flood damage (including NFIP claims), received federal assistance from agencies like FEMA, and disclose all known flood damage that occurred during their ownership—even if no insurance claim was filed.
Q2. How does California's natural hazard disclosure differ from Florida's flood disclosure? California uses a comprehensive Natural Hazard Disclosure Statement that covers six distinct hazard categories: special flood hazard areas, dam inundation zones, very high fire hazard severity zones, wildland fire areas, earthquake fault zones, and seismic hazard zones. In contrast, Florida's disclosure focuses exclusively on flooding risks. Additionally, California allows third-party professionals to prepare disclosure reports, while Florida requires sellers to personally complete the statutory form.
Q3. Do landlords need to provide flood disclosures to tenants in both states? Yes, but with different requirements. In Florida, landlords must provide flood disclosures for lease agreements of one year or longer beginning October 1, 2025. In California, Assembly Bill 646 requires landlords to provide a tenant flood hazard disclosure form for leases entered on or after July 1, 2018.
Q4. How much does flood insurance typically cost in Florida and California? Florida NFIP premiums range from $190 to over $2,000 annually depending on coastal proximity and elevation, with policies in lower-risk zones averaging around $700. Costs vary significantly by location—Miami neighborhoods like Brickell and Miami Beach face higher premiums than areas like Pinecrest or Coral Gables. Interestingly, 29% of NFIP claims originate outside designated high-risk flood areas.
Q5. What happens if a seller fails to provide proper hazard disclosures? Consequences differ between states. In California, incomplete Natural Hazard Disclosure statements could result in damages up to the entire property value, while incomplete Transfer Disclosure Statements typically limit damages to repair costs. California buyers also receive three days to rescind after late disclosures (extended to five days if mailed). Florida's specific penalties for non-disclosure are determined by the statutory requirements under Sections 83.512 and 689.302.